Three Red Sea addresses, three different buyers. A practical comparison of pricing, growth, rental demand and daily life in Hurghada, El Gouna and Sahl Hasheesh.
Ask three buyers where to purchase on the Red Sea coast and you will get three different answers. That is not because the market is confusing. It is because Hurghada, El Gouna and Sahl Hasheesh are three different products with three different jobs.
Hurghada is a working city with a resort economy attached. El Gouna is a purpose-built town with a marina, a film festival and a branded identity. Sahl Hasheesh is a master-planned bay with controlled supply and a quieter rhythm. Comparing them on price alone is like comparing a city apartment, a marina townhouse and a gated beach villa. The useful question is what you want the property to do for the next ten years.
The short answer
- Income first: Hurghada, particularly Al Ahyaa and the Mamsha promenade. Deepest guest pool, widest price range and the most comparable stock to benchmark against.
- Lifestyle first, income second: El Gouna. You pay a premium for a functioning town, and the premium shows up in the purchase price and in the running costs.
- Capital preservation and quiet: Sahl Hasheesh. Controlled supply, low density and a single master developer, with a lower headline yield than Hurghada.
- A first Egyptian purchase on a payment plan: Al Ahyaa and the northern corridor, where new-build supply and developer competition give you the most optionality.
Three addresses, three different jobs
Geography explains most of the difference. Hurghada runs from Al Ahyaa in the north, through the old town and south along the Mamsha promenade, with the airport inland to the west and Sahl Hasheesh further south. El Gouna sits about 25 km north of the airport. Sahl Hasheesh is about 18 km south of it.
Hurghada is a city first and a resort second, which is why it has the deepest rental market and the widest spread of quality. The northern district of Al Ahyaa is the expansion corridor, roughly 20 minutes from the airport and 15 minutes from El Gouna. Al-Kawther is the more mature southern district, next to the Mamsha promenade and minutes from the airport.
El Gouna was founded in 1990 by Samih Sawiris and is developed by Orascom. It has 10 km of coastline, 20 islands surrounded by lagoons, a marina, a golf course and an annual film festival. It behaves like a small town with its own rules, its own transport and its own service culture.
Sahl Hasheesh is a bay master-planned by Egyptian Resorts Company, which bought the land in 1995 and planned a 12-square-mile community. One master developer, one architectural language, one long beach. That control is the product.
How the pricing stacks up
Entry pricing is the first filter, and it is the least stable number in any guide. Rather than quote a price per square metre that will be out of date by the time you read it, compare the markets on relative position and ask each developer for a current price list.
- Al Ahyaa: the value entry. The lowest price per square metre in the Hurghada market, a steady flow of new compounds, and the widest choice of payment plans.
- Al-Kawther: the mid-market alternative. A mature district with limited remaining land, so it trades above Al Ahyaa per square metre and below the resort bays.
- Sahl Hasheesh: the premium bay. A single master developer and a controlled pipeline keep pricing firm, and beachfront or sea-view units carry the largest premium.
- El Gouna: the top of the market. Lagoon and marina frontage command the highest price per square metre on this coast.
Two caveats matter more than any single figure. First, asking prices are not transaction prices. Second, the cheapest unit in a premium area is usually small, so entry tickets overlap far more than the per-metre gap suggests. A 55 m² garden-view apartment in Sahl Hasheesh and a 90 m² compound unit in Al Ahyaa can land in a similar total bracket.
Ask for the net internal area, the view, the finishing specification, the service charge and the payment plan. Those five variables explain more of the price difference than the headline rate.
What has driven values
All three markets have risen in EGP terms over the past three years. The northern value districts have risen fastest in percentage terms because they started from a lower base, while the premium addresses have grown more slowly in percentage terms because they were already priced as premiums.
In euro or pound terms, currency movement has muted some of that gain, though values have held over a three-year hold. The lesson is not to chase the highest percentage. A lower-base district can post strong growth and still leave you with a less liquid asset at exit.
Where the rental guests actually are
Market estimates for the twelve months to August 2026 put the median Hurghada short-let at 52% occupancy, an average nightly rate of EGP 3,261 and annual revenue of about EGP 633,000. There were 3,897 active listings, up 69.5% year on year. International guests made up 78.6% of demand, with Germany the largest source market.
Studios achieved the highest occupancy at 56%, which fits the city’s short-stay, couple-heavy guest mix. Listings near Mangroovy Beach earned a 49% location premium. Seasonality is high, with demand peaking in October and August and weakest in February.
The national backdrop supports that demand. Egypt welcomed nearly 19 million tourists in 2025, up 21% on 2024, and Hurghada airport was one of the four main arrival points.
El Gouna and Sahl Hasheesh compete on a different axis. Both target a higher-spend guest, and both carry a higher purchase price and service charge, so the yield on capital is usually lower. The compensation is appreciation and a guest profile that is less sensitive to discount pricing.
A premium address is not a better investment. It is a different investment, with a different buyer at exit.
The costs that decide the comparison
The purchase price is the least interesting number in this decision. The running costs and exit costs separate a good decade from a mediocre one.
- Buyer-side costs: budget 4 to 5% of the price for notary, legal and registration work. The 2.5% real estate disposal tax typically falls to the seller.
- Service charge: varies widely by community, unit size and year. Ask for the written schedule, what it covers, how it escalates and whether there is a one-off maintenance deposit. Do not compare two compounds on headline price without comparing the charge.
- Annual real estate tax: 10% of the net assessed rental value after a 30% residential deduction.
- Exit: the 2.5% disposal tax is charged on gross sale value, not on your gain, and acquisition cost does not reduce it. Roundtrip costs land around 6 to 8%.
Which buyer are you?
You want income and liquidity. Buy Hurghada. Accept construction noise, traffic and a wide quality range in exchange for the deepest guest pool and the easiest resale.
You want a town, not a compound. Buy El Gouna. The marina, restaurants, schools and festival are the product, and you will use them. Do not underwrite the purchase on yield alone.
You want quiet and controlled supply. Buy Sahl Hasheesh. Fewer neighbours, a long beach and one architectural language. Expect a lower headline yield and a purchase you should be ready to hold.
You want new build on a payment plan. Stay in Al Ahyaa and the northern corridor. More developers, more stock and more room to negotiate on specification and handover terms.
Where our portfolio sits
Al Arabia builds in Al Ahyaa in the north and Al-Kawther in the south, the two districts that bracket the city. Al Ahyaa has led the city’s northward expansion and still offers the lowest entry point per square metre. Al-Kawther is the mature alternative, with established infrastructure, the Mamsha promenade nearby and a short drive to the airport.
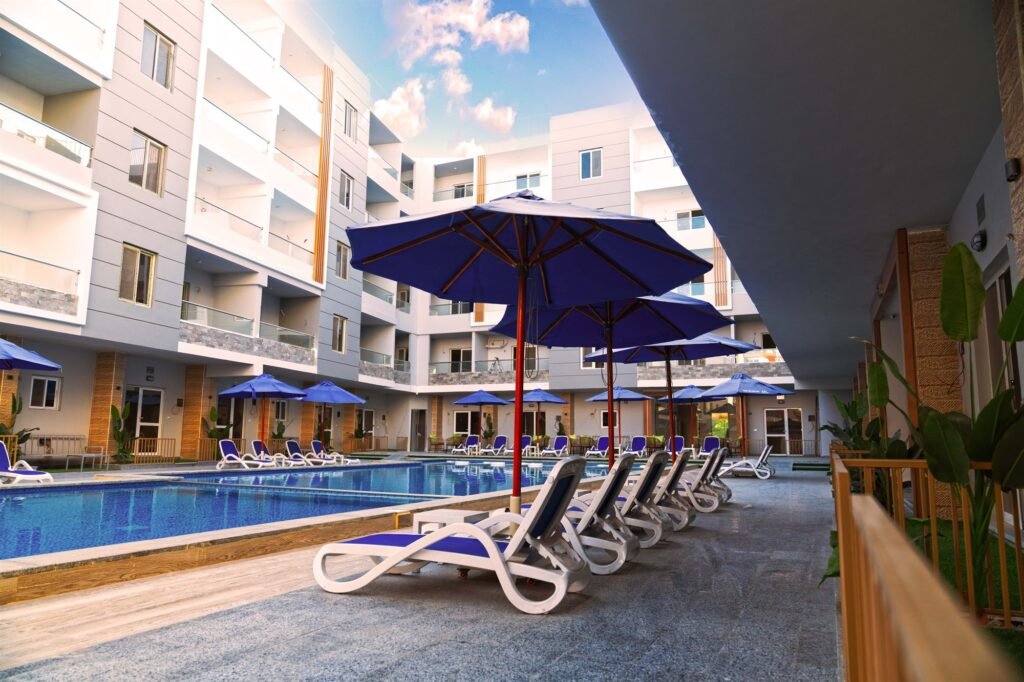
Our communities are deliberately low-density and beach-adjacent, with resort services and rental management on site. Mark Resort in Al-Kawther and Athena Resort in Al Ahyaa are the current releases. You can compare the full portfolio on the Projects page.
If you are deciding between the three addresses, bring your numbers to a conversation rather than a brochure. The right answer depends on whether you need income, use or both.
For current units, prices and payment plans, message our team on WhatsApp.
Ready to talk it through?
Our team can walk you through the details for any of our communities.